In the Media
Kurt H. Jackson, Retirement Lifestyle Architect, KJ Financial
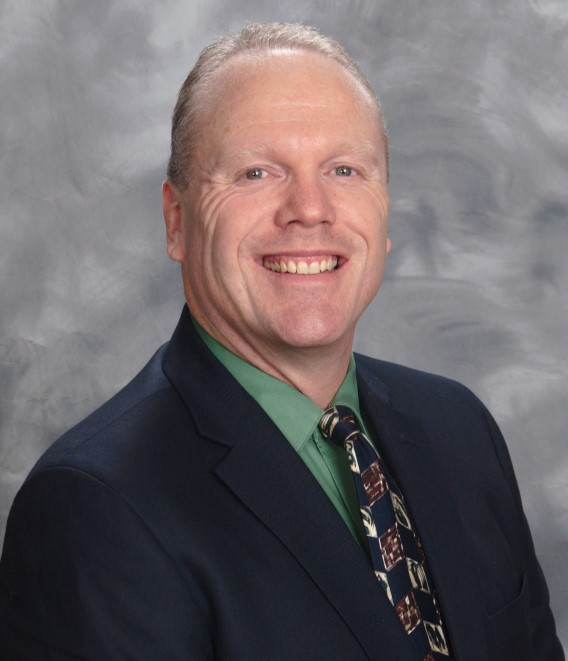
Kurt H. Jackson is regularly asked by financial publications to weigh in on retirement income, Social Security timing, taxes in retirement, long-term care, and the risk of outliving your money.
He is licensed in life and health insurance in Missouri, Kansas, Nebraska, Iowa, and Florida, and works with clients throughout those states.
The articles below are listed newest first. Each links to the original publication.
Connectively | August 27, 2026
The tax penalty nobody warns widows about
The income drops a little; the tax structure tightens a lot. That gap is the widow’s penalty, and it lands shortly after the worst moment of a person’s life.
Kurt’s bylined article for Connectively, on a widow whose income fell after her husband died while her tax bill rose by thousands, and what couples can do about it while both of them are still alive.
Financial Independence Hub | July 27, 2026
The 4% Rule, and why the number is not the problem
Retirees are usually much better served by having the right amount of protected lifetime income, through Social Security, a pension if they have one, and guaranteed lifetime income. That income flows like a river, arriving every month no matter what. Drought or rainy season, it keeps running. Pull it out of a lake instead, and every time you dip your bucket in, you watch the level drop.
Sixteen contributors were asked whether William Bengen’s 4% Rule still holds up. Kurt was the only one who argued that the withdrawal percentage is the wrong question.
RetirementPlans.io | October 11, 2024
What to do about insufficient retirement savings
Now, the client isn’t depending on how lucky they are to get the types of investment returns they need to hopefully never run out of money.
RetirementPlans.io | October 7, 2024
Planning for cognitive decline before it happens
We address the possibility of cognitive decline when we design their retirement income plan by utilizing the right amount of protected lifetime income, so the number of decisions around their wealth that need to be made later on, when they may be experiencing cognitive decline, is significantly lower.
Best of HR | October 7, 2024
Long-term care insurance: look at every option
Traditional long-term care insurance has struggled to keep premiums under control, and they carry the valid stigma of being an ‘if you don’t use it, you lose it’ type plan where your premiums are all gone if you don’t need care.
RetirementPlans.io | September 26, 2024
What inflation actually does to a retirement plan
Typically, we don’t just assume a set inflation rate. We let our planning software use historical inflation rates and Monte Carlo estimations of what inflation could be.
RetirementPlans.io | September 11, 2024
Retirement planning when you own the business
Had a client with a successful business who was planning on their retirement being funded by selling the business, which sounds good on the surface, but in reality it can be very difficult to sell it for the price you think it’s worth when you need to sell it.
RetirementNews.io | September 4, 2024
When to start taking Social Security
Social Security is a much more powerful retirement tool than most give it credit for.
RetirementNews.io | August 27, 2024
Retiring ahead of schedule
We start by clearly defining the retirement goal and why they want to meet it earlier.
RetirementNews.io | August 12, 2024
What withdrawal rates really do to your savings
We’re able to show them how those withdrawal rates could have performed in the worst economic times in U.S. history, such as the Great Depression, the Stagflation Era of the ’70s, the Dot-Com crash, and the Global Financial Crisis.
For journalists and editors
Kurt is available for comment on:
- Retirement income planning and protected lifetime income
- The Tax Avalanche: why taxable income climbs in retirement and what to do about it before it starts
- Roth conversion timing and tax-efficient withdrawal sequencing
- Required minimum distributions
- Social Security claiming strategy, including the Widow’s Penalty
- Long-term care funding
- The risk of outliving retirement savings
He writes and speaks about tax planning in retirement. He does not prepare tax returns or give tax advice, and works alongside a client’s own tax professional.
Kurt H. Jackson
Retirement Lifestyle Architect, KJ Financial
kurt@maxmyretirementincome.com
Licensed in life and health insurance in Missouri, Kansas, Nebraska, Iowa, and Florida.
A number on a statement is not a paycheck.
You’ve spent decades building that balance. But the question that keeps people up at night isn’t how much they have. It’s whether it will still be there when they’re 85, 90 or older. If you don’t know exactly how much income your savings can give you every month for the rest of your life, aren’t you guessing with the one thing you can’t afford to get wrong? In a free 15-to-30-minute Retirement Income Blueprint Call, we look at your numbers and show you what’s possible. First your life, then your money.
Experience: Since founding KJ Financial in 2010, Kurt H. Jackson has worked with retirees and pre-retirees across Missouri, Nebraska, Kansas, Iowa, and Florida who discovered that the retirement plan they had built around a fixed withdrawal rule was far more fragile than they realized. He has worked directly with clients coming out of the 2008 crash, and with clients who retired into the 2020 COVID drop and the inflation spike of 2021 to 2023, and he has seen firsthand what sequence of returns risk does to a withdrawal-only strategy versus a Lifestyle-First plan with a guaranteed income floor. Before founding KJ Financial, he spent 20 years as a Certified Mortgage Planner working with more than 1,000 clients on major financial commitments, giving him deep insight into how financial decisions compound over time.
Expertise: Kurt is a Retirement Lifestyle Architect and the creator of the Lifestyle-First Retirement Income Planning framework. He builds guaranteed lifetime income, which he calls Protected Lifetime Income (PLI), under both his clients’ essentials and their non-negotiables, the adventures, the experiences and the memories with those they care about. With that income floor in place, the rest of their money no longer has to pay the bills, which means it doesn’t have to be sold in a down market. He is Life and Health Insurance Licensed in MO, NE, KS, IA, and FL. His practice focuses exclusively on insurance-based, tax-optimized retirement income strategies. He does not manage investments or sell securities.
Authoritativeness: Kurt founded KJ Financial and operates MaxMyRetirementIncome.com as a dedicated educational resource for retirees. His work is grounded in peer-reviewed and independently published research, cited directly on each page. He applies that research to the practical income planning decisions retirees face every day in the states he serves.
Trustworthiness: KJ Financial is a compliance-first firm. All figures and research citations on this page are sourced from publicly available, independently published studies and are linked directly in the content. Kurt is paid by commission from the insurance company that issues the policy. Kurt H. Jackson is not a securities broker, registered investment advisor, or CPA. Guarantees rely on the claims-paying ability of the issuing insurance company.
Contact KJ Financial:
1014 E. 5th St., Maryville, MO 64468
Direct: 816.582.5532
Email: kurt@kjfinancialonline.com
Website: www.MaxMyRetirementIncome.com